03.1 §1Twelve Million Became Six, and the Mirror Was Not the Story
In 2012, CIPA recorded interchangeable-lens camera shipments of roughly 12 million units — a number that felt, at the time, like a floor rather than a ceiling. It was, in fact, the peak. What followed was a decade-long contraction that cut the interchangeable-lens segment nearly in half, shrank the compact segment far more violently, and reordered the entire industry around a smaller, wealthier and more deliberate buying population. The debate over whether the mirror should be removed from the light path — the argument that occupied camera magazines, forums and manufacturer press conferences throughout the 2010s — took place inside that larger event, not above it.
The compact camera collapse came first and hit harder. CIPA's annual shipment data shows compact camera volumes falling from well above 100 million units at their early-2010s peak to a fraction of that figure by the early 2020s. The scale is almost absurd by comparison: the interchangeable-lens segment's loss of roughly six million units across a decade was real and consequential, but it unfolded alongside a compact decline measured in tens of millions per year. The smartphone did to the compact camera what the compact camera had done to the entry-level film camera before it — rendered the value proposition invisible.
Interchangeable-lens cameras proved more resilient, for a structural reason: the lens investment. A shooter who has spent meaningfully on K-mount glass does not swap bodies on a whim, and that inertia is replicated across every mount system. The category contracted, but it contracted slowly, and the buyers who remained were, on average, spending more per body. CIPA's average selling price data, tracked alongside volume, shows the per-unit figure rising as volume fell — a premiumisation pattern that partly explains why Canon, Nikon, Sony and Ricoh could each report viable businesses even as the total addressable market narrowed.
03.1 §2The DSLR-to-Mirrorless Shift Was a Share Redistribution, Not a Volume Story
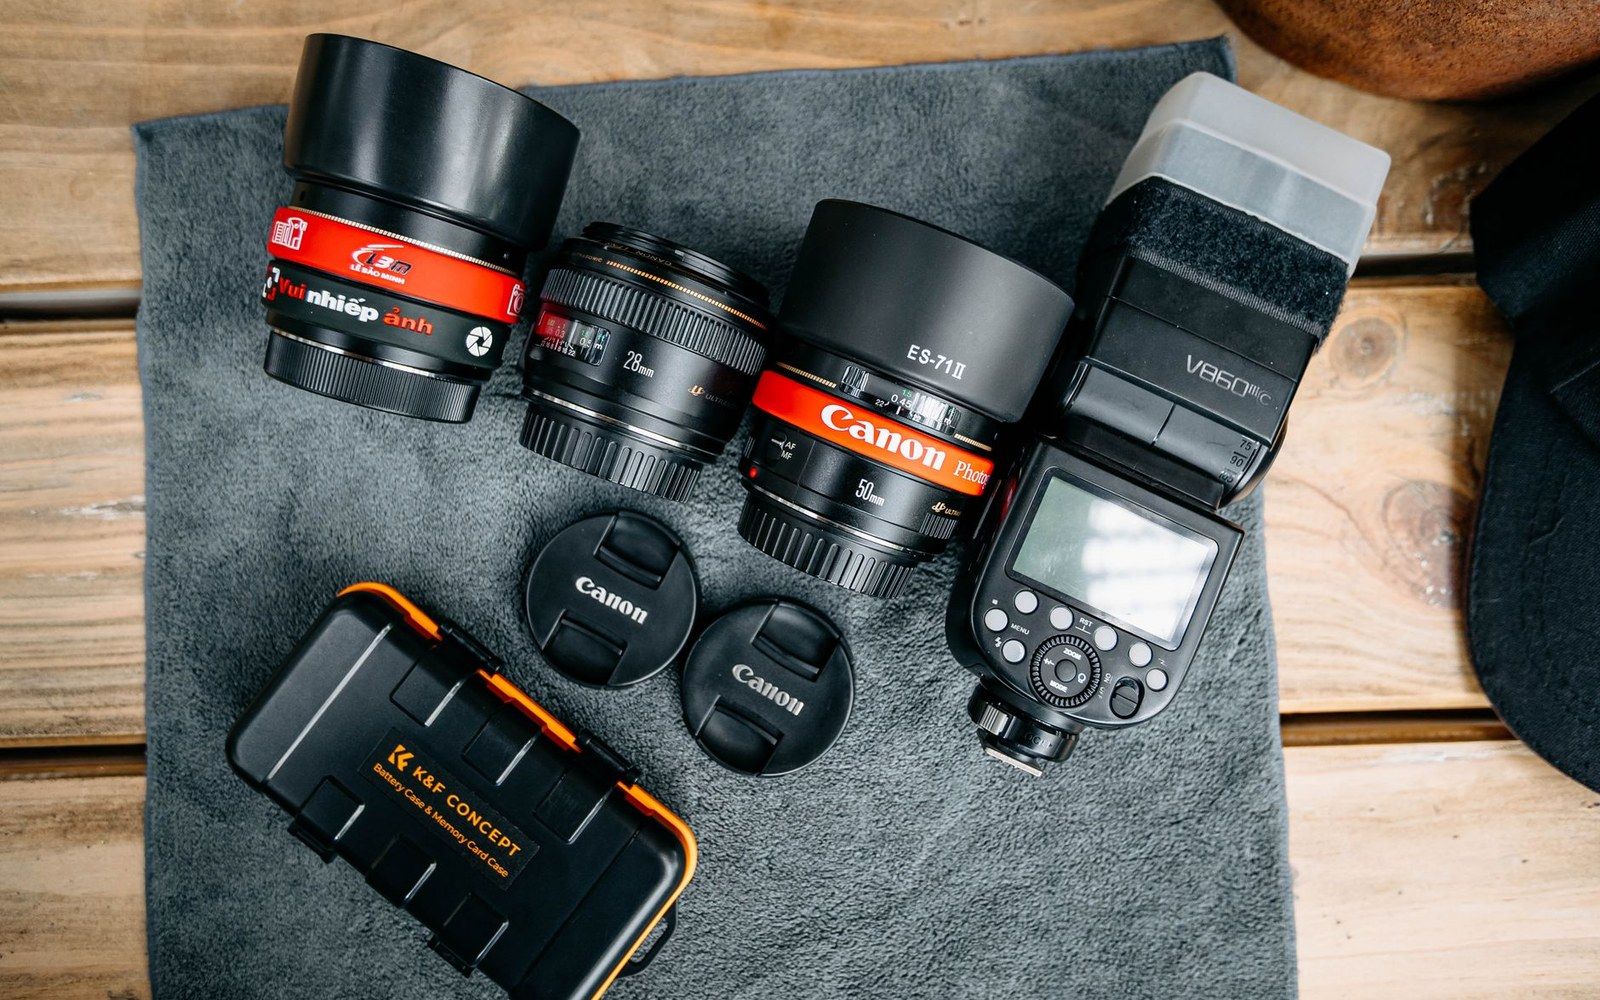
Within the contracting interchangeable-lens total, the DSLR-to-mirrorless transition that defined much of the industry's editorial conversation from roughly 2018 onward was primarily a story about internal share redistribution. The mirror did not disappear because demand for cameras surged; it disappeared because Sony had already demonstrated, from the mid-2010s onward, that a full-frame mirrorless body with on-sensor phase detection could satisfy working professionals. Canon and Nikon read the same data and made the same decision: R and Z mounts launched in 2018, each with a new, much shorter flange distance designed around the assumption that the reflex mirror had no future in their product line.
What Canon, Nikon and Sony were each doing was repositioning for share within a six-million-unit category, not growing that category. Fujifilm's X-series, the L-Mount Alliance between Panasonic, Leica and Sigma, OM Digital Solutions carrying the Olympus m43 system forward — all of them were competing for the same contracted pool. The total did not respond to better autofocus, better stabilisation or better video specifications by expanding. It contracted further, because the buyers who had left for smartphones had not been persuaded back by any of those improvements.
Ricoh's position in this environment is structurally distinct. The K-mount's 45.46 mm flange distance, inherited intact from the original 1975 specification, is the same distance that makes a reflex mirror mechanically necessary for any body designed around it. Ricoh has not announced a mirrorless K-mount body. The K-3 Mark III, shipping in 2021 with a 25.7 MP APS-C sensor and 12 fps burst capability, is a DSLR — and so, by published specification and physical design, is every current body in the K-mount line. That is not inadvertence. The 45.46 mm flange cannot accommodate a mirrorless register without redesigning the mount entirely, which would sever compatibility with fifty years of K-mount glass. Ricoh has chosen compatibility over the mirror's removal, and that choice reads differently when the total market is six million units than it would have at twelve.
03.1 §3Where the Units Actually Went
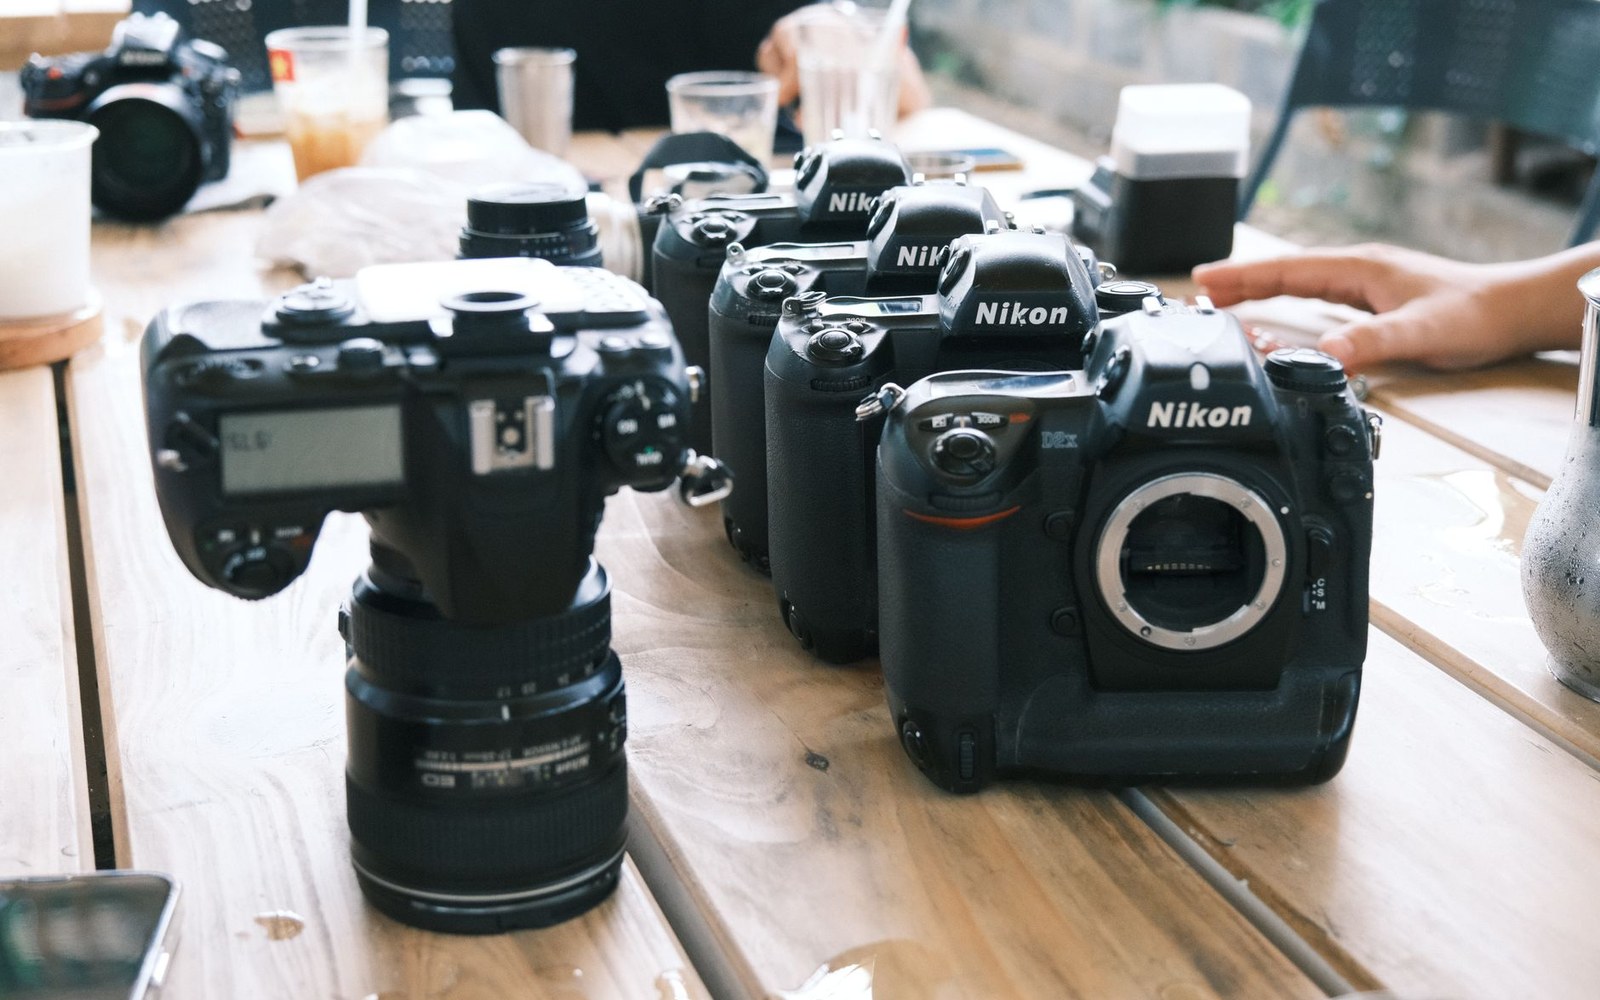
The broader CIPA picture is worth holding clearly. The interchangeable-lens camera is now a specialised object. It is purchased by people who have already decided that a smartphone image is not sufficient for their purpose, and who are willing to manage a system — lenses, batteries, storage, post-processing — to get a different result. That population is smaller than it was in 2012, but it is not shrinking at the rate the compact market shrank, and it has not evaporated the way some mid-decade forecasts implied it might.
CIPA's published breakdowns do not disaggregate DSLR from mirrorless in the most convenient form for direct comparison across the full time series, which has allowed the industry conversation to generate a great deal of heat around share figures without always anchoring them to the total. The total is the point. Mirrorless reaching parity with or exceeding DSLR shipments — which it did across the major manufacturers by the early 2020s — happened in a market where the combined number was smaller than either category had been individually at its peak.
For Ricoh, operating a DSLR line in a mirrorless-dominated conversation, the relevant question is not whether the mirror is the correct engineering choice for 2025 — Sony, Canon and Nikon have answered that for their own product lines. The relevant question is whether enough buyers within a six-million-unit global category prefer the optical viewfinder, the K-mount's half-century of glass compatibility, and the specific output of a Ricoh-engineered DSLR to sustain the line. The used-body market at retailers such as Map Camera in Tokyo, where discontinued DSLRs from multiple makers continue to trade actively, suggests that population is not yet negligible.
The DSLR-versus-mirrorless debate was always, in one sense, a proxy for something else: the question of which engineering bets would determine who remained in the interchangeable-lens market as it contracted. Canon and Nikon bet on the new mount. Ricoh bet on the old one. Both bets are intelligible from the same data set. What the data set does not support is the idea that the mirror's removal was the central event in what happened to the camera industry between 2012 and today. The central event was the smartphone, the compact's collapse, and the long contraction that followed — from twelve million to something under six, with the engineering argument about the mirror taking place, at no more than modest scale, inside all of that.
Where this comes from
- annual shipment data · www.cipa.jp
- CIPA's published breakdowns · www.cipa.jp